If something happens, your family will know where it all is
You have a big job, a few rentals, maybe an LLC or two. Does your spouse know which LLC owns the duplex, who the lender is, or where the operating agreement is kept? This binder puts your whole portfolio on paper, so nobody is left guessing.
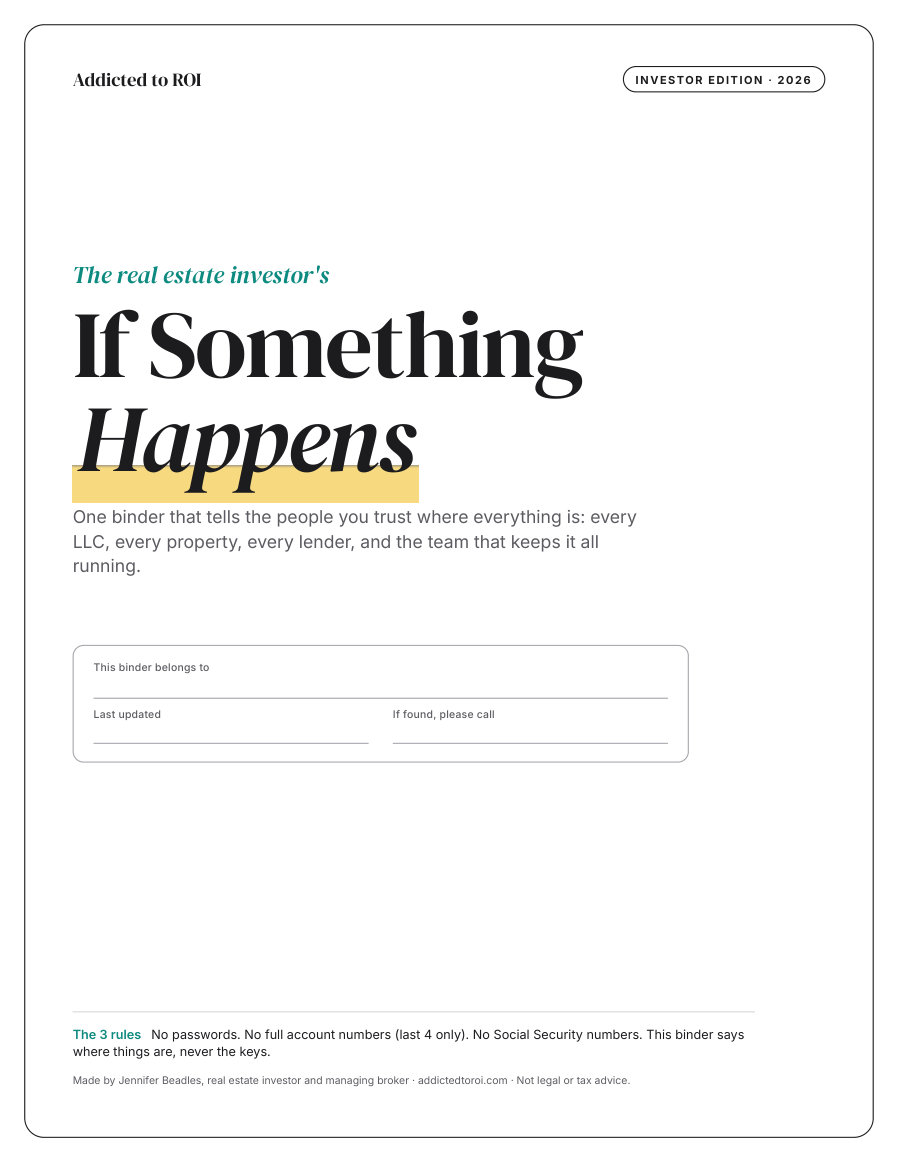
Regular planners stop at “bank account, life insurance”
I have invested in real estate for 17+ years, and I am a managing broker in Arizona and Washington. Every “when I die” planner I looked at asked for a bank account and a life insurance policy. That is it.
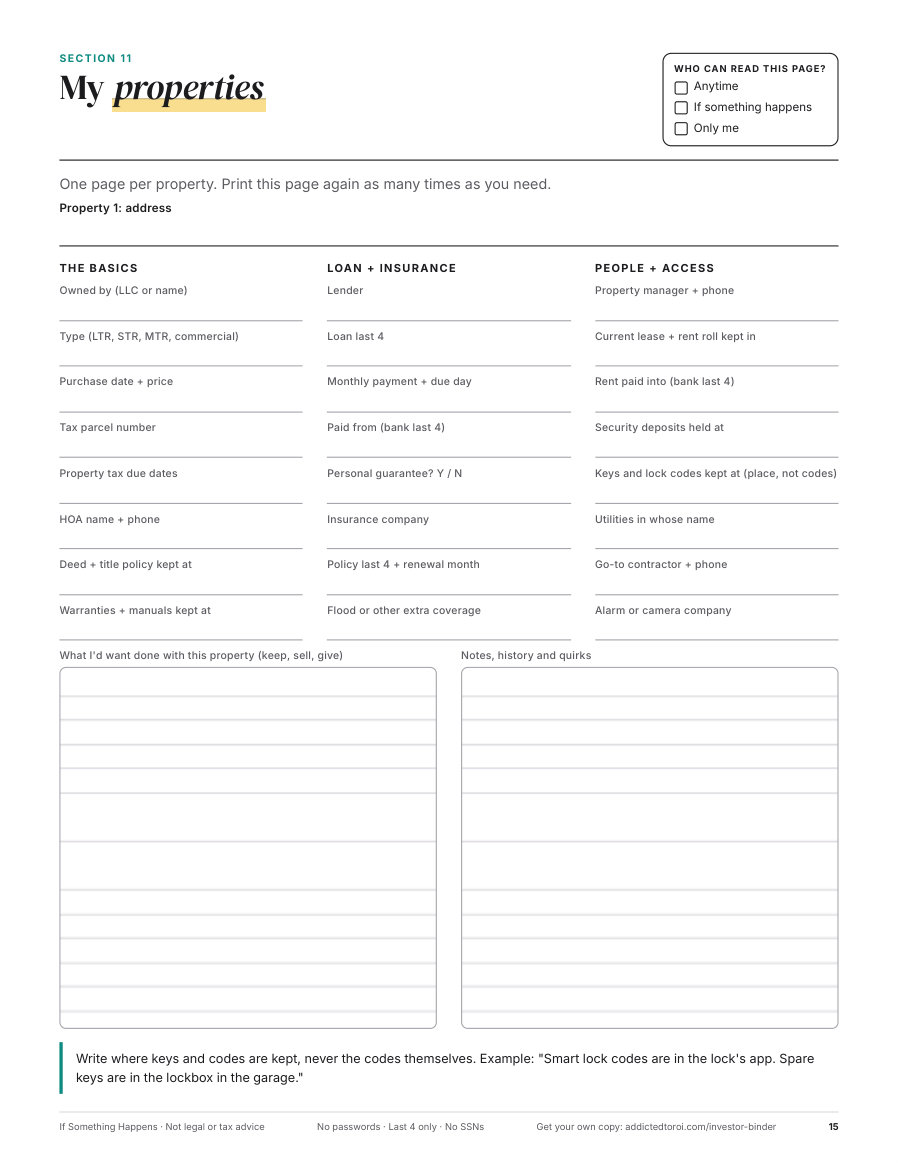
An investor has LLCs, lenders, a property manager, a CPA, leases, and the logins to the books. So I built the binder I wanted: one page per LLC, one page per property, and a page for the team that keeps it all running. Only 24% of U.S. adults even have a will.1 A will says who gets what. This says where it all is.
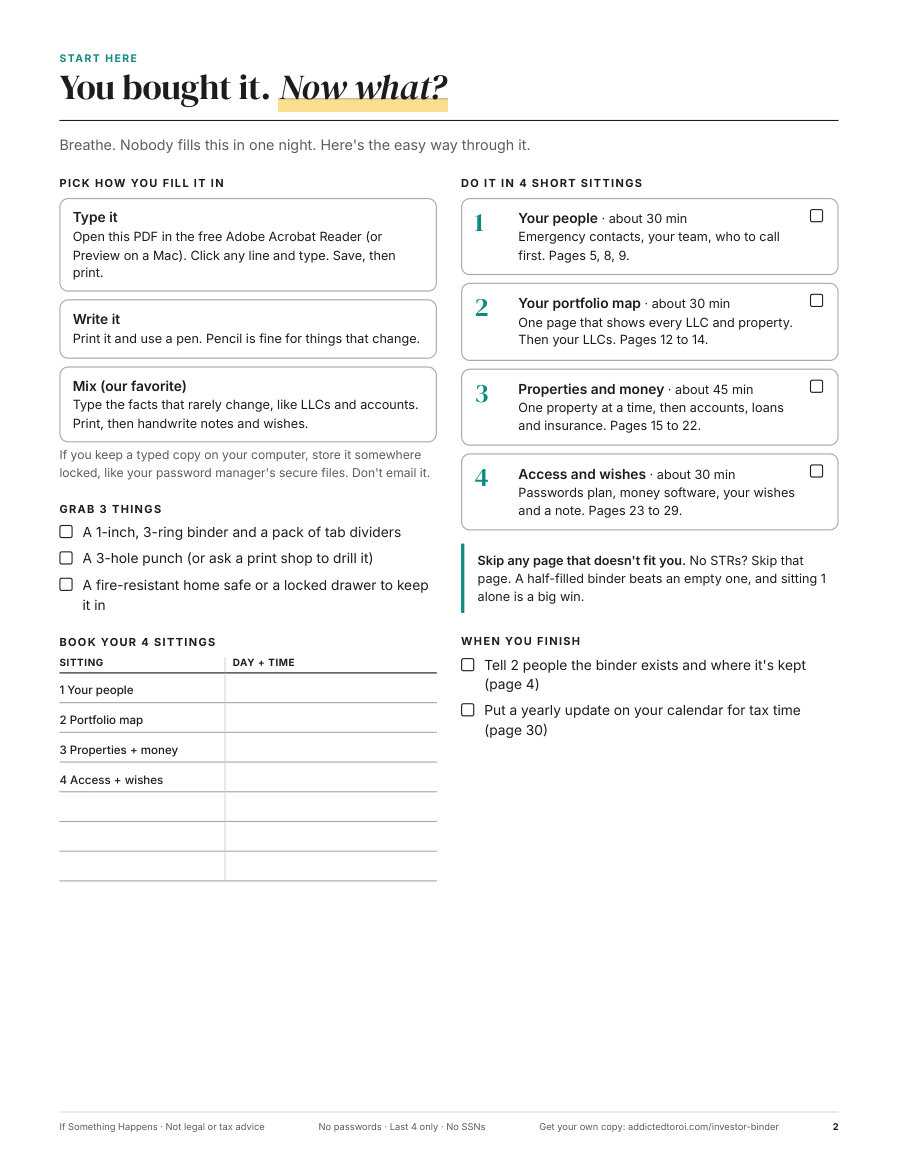
See what you are filling in
25 sections, made for investors
- 1Start here: 4 short sittings, not one long night
- 2How to use it + who can read each page
- 3Read this first: the first 72 hours
- 4The first 30 days
- 5About me + where the originals are
- 6Emergency contacts
- 7My team: CPA, attorney, PM, lenders, agent
- 8Healthcare directive + my wishes
- 9Will, trust and powers of attorney
- 10My portfolio on one page
- 11My LLCs: owners, EIN last 4, who can sign
- 12My properties: one page each
- 13Bank, brokerage and retirement accounts
- 14Life, disability and umbrella insurance
- 15What I owe, including personal guarantees
- 16What is owed to me + syndications
- 17Bills that pay themselves
- 18Passwords + digital life: Apple and Google legacy steps
- 19Money software + logins: QuickBooks, bank portals, rent tools
- 20Other accounts that matter
- 21Short-term rentals: how they run
- 22Tax records: past 1031s, cost seg, depreciation
- 23Final wishes
- 24A note to my people
- 25Annual update checklist
You decide who sees each page
Each page has three tick boxes at the top. Tick one, then file the page behind the matching tab in your binder.
Anytime
Emergency contacts, your doctors, your healthcare directive. The pages someone needs in a hospital waiting room.
If something happens
Accounts, policies, LLCs and lenders. Opens only if you die or cannot act for yourself.
Only me
Private notes for your own use. Keep them in a separate envelope if you like.
Update it once a year, at tax time
Most people fill in a planner once and never look at it again. This one ends with a one-page yearly checklist you run when you send papers to your CPA. You are already gathering them. States hold about $70 billion in unclaimed money, and about 1 in 7 Americans have some.2 A current binder keeps yours off that list.
Before you buy
My CPA and my attorney already handle this.
Is it safe to write all of this down?
I only have one rental. Is this overkill?
Do I print it or type in it?
Is another subscription involved?
Is this legal or tax advice?
Get it today. Fill in the portfolio map tonight.
$29, one time, no subscription. Pay on Stripe's secure checkout and you land on the download page right away. Type in it, print it, or both.
Not legal or tax advice. The binder is an organizer and does not create or replace a will, trust, power of attorney or healthcare directive. Laws differ by state.
Sources:
- Caring.com wills survey, 2025
- U.S. Senate Banking Committee letter to NAUPA, April 2026 and ClickOrlando, May 2026
- Vault prices: Everplans ($99.99 a year) and Trustworthy (up to $480 a year).